Activity
Mon
Wed
Fri
Sun
Nov
Dec
Jan
Feb
Mar
Apr
May
Jun
Jul
Aug
Sep
Oct
What is this?
Less
More
AI Automation Society
474.2k
Free
Build Market Close
748
5.0
Free
Fearless Prospecting Group
3.5k
Free
AI Turbo
44
Free
Ranking Wizard Mastermind
132
Free
Digital Edge
136
Free
Local Newsletter Launchpad
2.2k
4.9
Free
Faceless Tuber School
1.2k
$7/m
12 contributions to Money Broker Society

🚀
18d •
🎁 FREE MINI COURSE: COVER 100% OF YOUR REAL ESTATE DEALS
I've done 17 real estate deals over the last 2 years, and one of the biggest things I've learned is how powerful ACCESS TO CAPITAL can be. Here's the basic strategy we teach: 1️⃣ Get $100K–$200K+ in business funding 2️⃣ Convert available credit into cash 3️⃣ Use the capital for things like: • Down payments • Closing costs • Rehab • Gap funding 4️⃣ Buy + improve the property 5️⃣ Once the property is ready and you meet the lender's requirements, potentially cash-out refinance or sell 6️⃣ Use the refinance proceeds to pay down the business credit or flip to pay it down Now you've used leverage (OPM) to cover the acquisition + project costs instead of tying up all your own cash. Then you can work toward recycling that capital into the NEXT deal. 🔄 I put together a FREE MINI COURSE breaking down exactly how this strategy works. 🔥 Comment “REAL” below and I'll send you the mini course. Already have a 700+ credit score and want us to look at your funding options? You can also book a 1-on-1 funding analysis. https://apply.fundingvault.io/ Need to fix your credit first? Let me know. We have a low-cost credit repair option designed to help you work toward becoming funding-ready. 👇 Comment “REAL” for the free Real Estate Funding Mini Course.


1 like • 18d
Real!!
🚀
Aug 7 •
How Your Kids Can Win
The cheapest insurance you will ever buy is on a healthy 5 year old. And most parents never find out until it costs ten times more. Here is what almost nobody explains. When you fund a cash value policy on a child, you are not buying a death product. You are buying them 60 years of tax advantaged compounding. And you are locking in their insurability forever. Think about that second one. Your kid gets diagnosed with something at 27. Type 1 diabetes. A heart condition. Anything. Now they are uninsurable or paying triple. The policy you started at 5 does not care. It is already issued. Already locked. Already growing. That is a gift you cannot buy back later. Now the money side. You fund it while they are young. By the time they are 25 there is real cash value in there. They borrow against it for a car instead of financing at 11 percent. They borrow for a down payment instead of draining savings. They borrow to start a business instead of begging a bank. And every time, the cash value keeps compounding as if they never touched it. You did not hand them money. You handed them a system. They become their own bank at 25 instead of figuring it out at 55. Here is the ugly statistic and facts. A 529 does not protect your family if something happens to your kid. And it does not protect your kid if something happens to you. Americans owe 1.87 trillion dollars in student loans right now. The average graduate walks out with 43,000 dollars of it. 529 plans were supposed to solve that. Most of them do not, because life refuses to follow the plan. A college fund pays for four years. A funded policy gets borrowed against, repaid, and borrowed against again for sixty years. Wealthy families have been doing this quietly for over a hundred years. 70 percent of family wealth is gone by the second generation. 90 percent by the third. Not because the first generation did not build enough. Because they transferred money without transferring the machine that made it.

2 likes • Aug 7
SEED
🚀
Jul 31 •
Whole Life vs IUL Explained — Free Guide
Everyone wants to talk about the 7% upside. Almost nobody explains the product that pays you when absolutely nothing goes right. That product is whole life insurance. And it is the most misunderstood asset a business owner can own. Here is what it actually is. You pay a fixed premium that never goes up. The insurance company guarantees your cash value grows every single year, usually 3% to 5%. Not projected. Not estimated. Guaranteed in the contract. On top of that guarantee, mutual insurance companies pay dividends. Some of these companies have paid a dividend every year for over 100 years. Through the Great Depression. Through 2008. Through 2020. Read that again. An asset that has never had a down year while the stock market had 26 of them. So why does anyone buy an IUL instead? Because IUL gives you more upside. Higher caps. More growth potential. Lower cost per dollar of death benefit. Here is the honest comparison. Whole life is for the business owner who wants certainty. You know the exact number on the exact date. You can plan around it. You can borrow against it. IUL is for the business owner who wants growth and can live with a range instead of a promise. Zero floor. Higher ceiling. More flexibility on what you pay in. Neither one is wrong. The wrong move is owning neither and keeping $200,000 sitting in a business checking account earning nothing while you wait for an opportunity. Cash that just sits there loses to inflation every year. Cash inside a properly structured policy grows, stays accessible, and hands your family a tax free check if you do not come home. That is why doctors, dentists, real estate investors and banks all own this. They are not chasing returns. They are building a floor to stand on. Want to know whether whole life or an IUL fits your situation better? Comment GUARANTEE for a free guide below. Or book a free strategy session at familybankingvault.com

4 likes • Jul 31
GUARENTEE
🚀
May 29 •
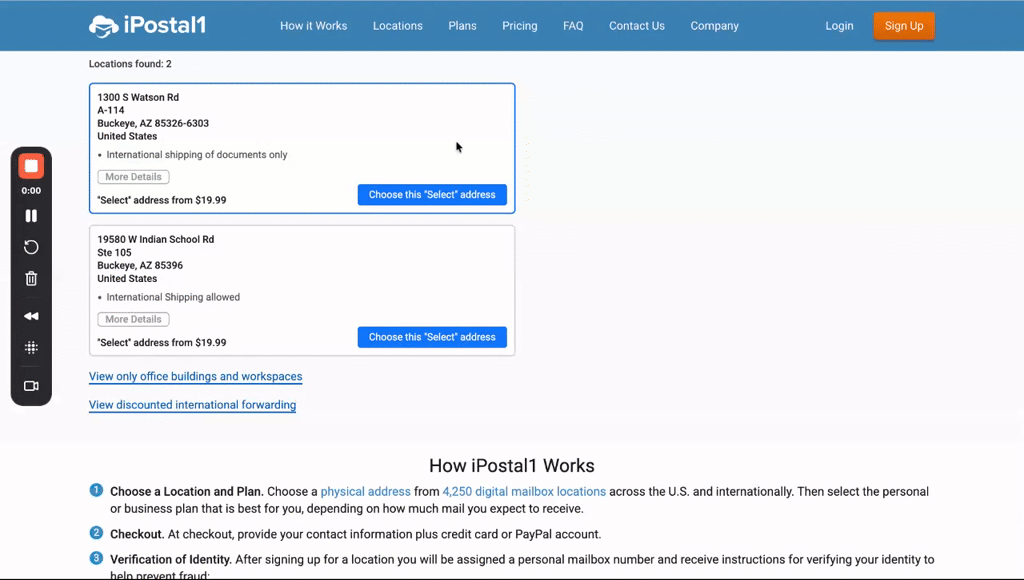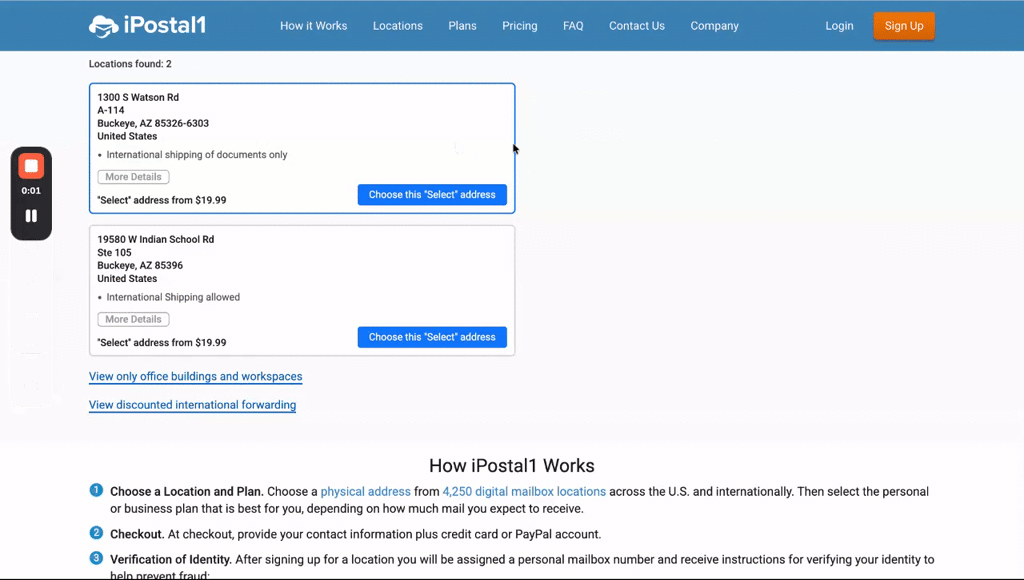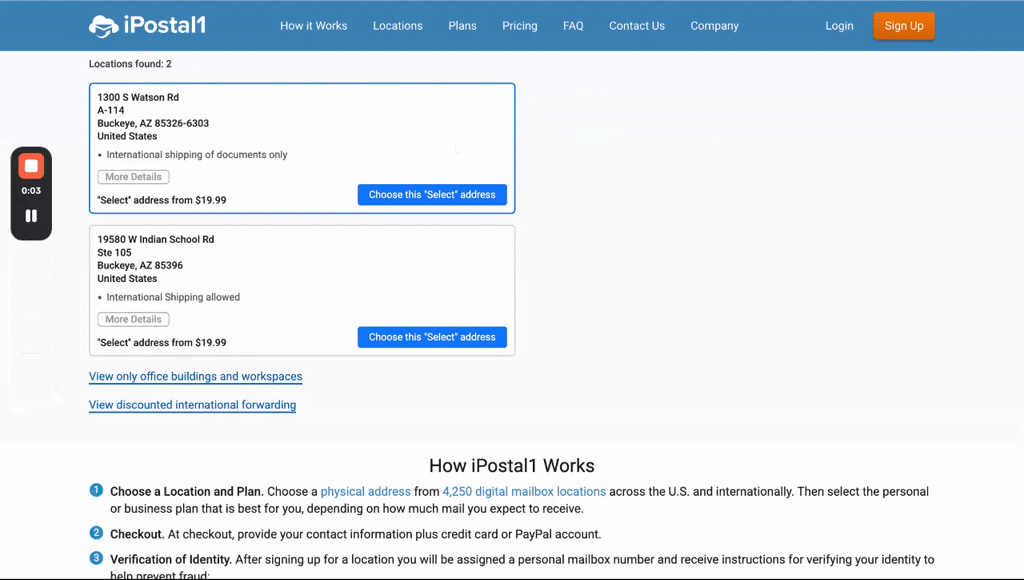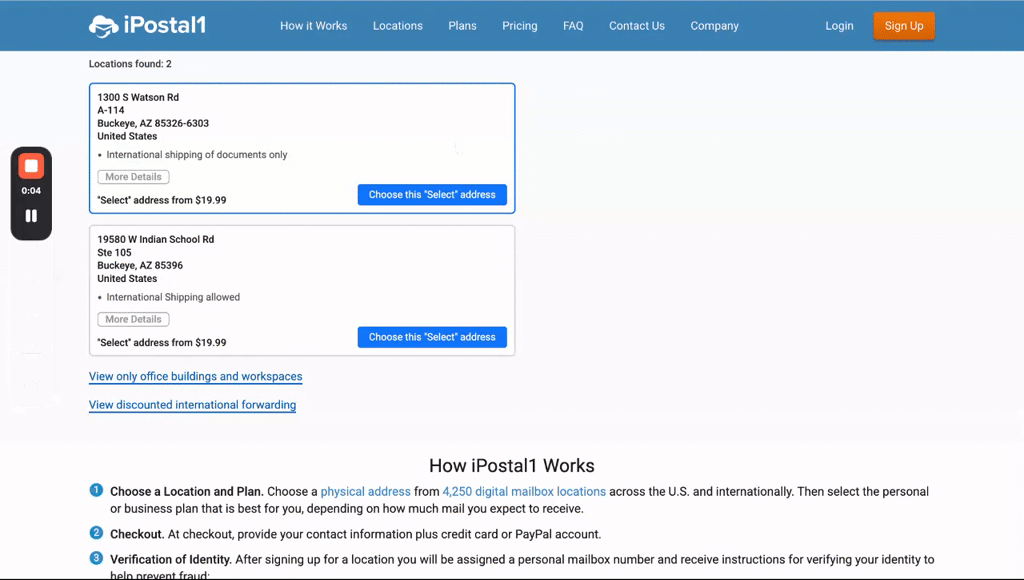
Virtual Addresses
Good morning, this is how you see if an address is HIGH RISK, virtual addresses are typically CMRA (commercial mailing receiving agency) which is marked as high risk. I show 2 different example of vendors, 1 is iPostal and one is DaVinci! (:
1 like • May 29
I feel VIP! DaVincivirtual.com for the win!
🚀
Mar 18 •
💳➡️💰 How to Turn Credit Into Cash (Most People Don’t Know This)
Ever wonder how people actually turn credit into cash? There’s a few ways to do it 👇 🔄 The Common Methods • Costco / Apple HacksBuy products → return → get refunded to debit/cash • Buying Groups. You purchase products → send to a reseller → they reimburse you 1:1 via check (cash) (You can even profit + stack points) • Online → In-Store returns old school method — still works in certain cases ⚠️ Other Options • Melio / Plastiq (~2.9%) Can work in some situations. Not ideal for real estate deals, but an option. 🔥 The Fastest Way (If You Value Time) If you’re busy… You can use a liquidation company. Typical fee: ~6% but after cash back: ~4.5% effective Example: $30,000 → ~$1,800 fee Now ask yourself… If that $30K goes into a deal that gives you: • Tax benefits• Appreciation • Cash flow • Tenant paydown Does $1,800 matter? No. 💡 So Is It Worth It? Yes. You’re trading a small fee for: Speed + leverage + opportunity 🎯 Want the Full Guide? If you want ALL the methods broken down step-by-step (free): Comment “CASH” below and I’ll send it to you. Also check your DMs after, a lot you never open them. 🤣

0 likes • Mar 18
CASH!
1-10 of 12
@tim-judge-2641
!!! FOLLOW ME !!! DADx5, Real Estate, Video Marketing, Local Networking http://LocalsJoin.US
Active 8m ago
Joined Nov 25, 2025
Greenwich CT
Powered by